


This post may include affiliate links.
#1
#2
#3
It sounds almost insultingly basic, but the trick is that you never really experience the money as available. If $100 automatically disappears into savings every payday, your lifestyle tends to adapt around what remains.
Trying to save “whatever is left at the end of the month” usually produces the fascinating discovery that somehow there is never anything left 😭
Basically, pay your future self before your current self discovers Uber Eats.
Most of us know that saving money is important, Pandas. Whether it's building an emergency fund for unexpected medical bills, covering a sudden car repair, or simply making sure we can cover basic expenses if something goes wrong, having money set aside can offer a real sense of security. But knowing we should save and actually managing to do it are two very different things. Even though saving is a sensible financial habit, plenty of people struggle to put money aside. A study conducted by ING Group across 13 European countries, involving nearly 14,000 participants, found that 29% of respondents reported having no savings, while another 36% had savings equivalent to just three months of living expenses. These figures highlight how financially vulnerable many households can be when unexpected costs arise.
#4
#5
#6
The situation has also raised concerns in the United States. A 2017 GoBankingRates survey found that 57% of Americans had less than $1,000 in savings, while 39% reported having no savings at all. Although these figures are several years old and don't reflect current savings levels, they illustrate how long-standing the challenge of building a financial cushion has been. When much of your income goes to rent, groceries, bills, and other essentials, saving can feel impossible. And even when you have a little money left over, it can be hard to know where to start or how to stay consistent.
#7
#8
BUT...only if you pay it off IN-FULL at the end of the month.
#9
Income, of course, plays a major role in how much people can save. Someone earning a comfortable salary may have more room to set money aside than someone struggling to cover basic necessities. Research has repeatedly found a relationship between household income and savings, with some studies suggesting that people below a certain income level have very little left to save after covering their expenses. However, income isn't the only factor that influences saving habits. Psychological factors, spending patterns, personal priorities, and the way people think about money can also affect their financial decisions. While no budgeting trick can make an inadequate income stretch indefinitely, understanding our habits can help us make better use of the money we do have.
#10
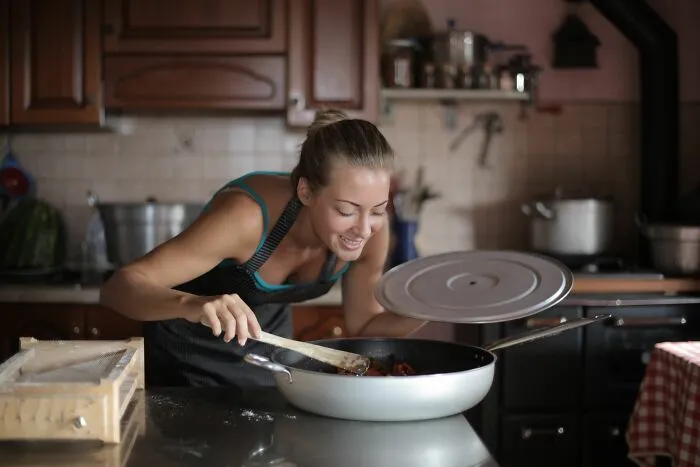
A meal that's $20 at a restaurant can be made for under $2. Edit: I'm looking at my go to simple vegetable Indian curry over rice, if I throw in chicken thighs (which I get bone in for dirt cheap) it doesn't even come up to $3 a serving. If you shop around you can find raw ingredients for cheap but you have to be comfortable cooking and prepping more. I like doing it (hence the username) and know I'm biased, but really if you want to save money this is the best way I've found.
#11
Ignore the coworker who says it's not worth doing because "they just take it all in taxes".
A pay check containing overtime pay may withhold more taxes as compared to a regular pay period (no OT), but the year-end tax filing will account for that.
I've had someone try to tell me this at every job I've had.
Same if anyone tells you that getting a raise just puts you in a higher tax bracket. Technically true, but only the earnings above that bracket are taxed at the higher rate.
Fake example: Employee gets a raise from 48k to 52k. One of the tax brackets lies at 50k- for this fake example, say the tax rate goes from 10pct to 15pct at that 50k line. The only wages that will be taxed at 15pct are dollars 50k to 52k. 10pct tax on that 2k would be 200, but 15pct tax on that 2k is 300. So you're paying an extra 100 dollars in tax for earning 2,000 dollars more. Still a large net gain, so take the raise.
#12
Wait 24 to 48 hours.
A huge number of online retailers use automated marketing systems that track abandoned carts. They will automatically email you a discount code (usually 10% to 20% off) with a subject line like "Did you forget something?" to get you to finish the transaction.
It doesn't work on every single website, but it works often enough that it is always worth a try if you aren't in a rush.
One book that explores this relationship between money and human behavior is The Psychology of Money: Timeless Lessons on Wealth, Greed, and Happiness by Morgan Housel. One of its central ideas is that building wealth isn't necessarily about earning a huge salary or buying all the things that signal success. It's also about what remains after we've spent our income. Housel explains that saving often requires resisting the urge to spend money to impress other people or keep up with their lifestyles. It's easy to feel pressure to upgrade our phones, buy the latest clothes, or spend on things that make us appear successful. But the money we don't spend can be just as valuable as the money we earn, especially when it gives us more security and choices in the future.
#13
I don't know where she learned that, but it definitely wasn't from me.
#14
#15
Another important lesson from Housel's book is that money can provide something more meaningful than material possessions: control over your time. Having savings can give you the freedom to leave a job that makes you unhappy, take time to care for a loved one, explore a new career, or handle an unexpected expense without immediately falling into debt. Of course, not everyone has enough disposable income to build a substantial safety net quickly, and financial security looks different for everyone. Still, even a modest amount saved over time can provide a little more breathing room when life doesn't go according to plan.
#16
#17
It sounds too simple to actually matter, but it kills a ridiculous amount of impulse spending. If you still want it after 24 hours, buy it. Most of the time the urge is gone and you realize you didn't actually need it.
It's basically a money-saving hack that costs absolutely nothing.
#18
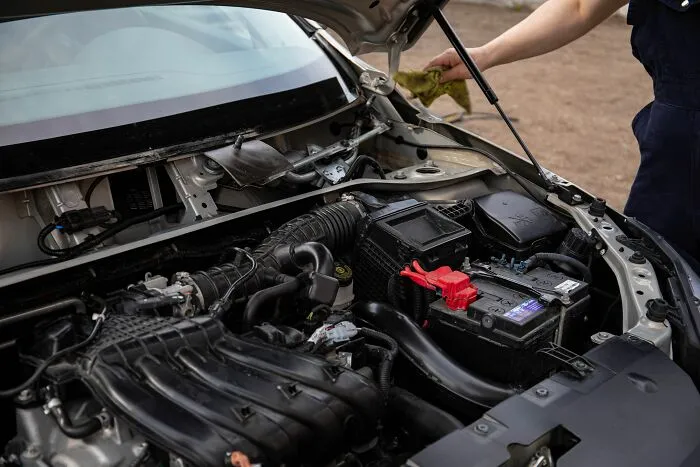
If you need a specialized tool for a car repair, like a torque wrench, a steering wheel puller, or an O2 sensor socket, you don't have to buy it. You just go to the counter and ask to borrow it. They will charge your card for the full retail price of the tool as a deposit. You take it home, get your car fixed, and bring the tool back a day or two later. They refund 100% of the money right back to your card.
It feels like you are getting away with something, but it is their actual business model. They know that if you are pulling apart your engine or suspension, you are going to need consumable parts like brake pads, fluids, or grease. By letting you use the expensive, highly specific tool for free, they guarantee you will buy the actual parts from them while you are standing in the store. It saves you from dropping $150 on a heavy piece of metal you will only ever use once in your life.
So, how can you make saving feel more achievable? Better Money Habits, an educational resource from Bank of America, recommends setting specific savings goals. Instead of simply telling yourself to save more, think about what you're saving for. It might be a holiday, a new car, a future home, or an emergency fund. Work out roughly how much you'll need and how long you have to reach your goal. Breaking a large target into smaller, manageable steps can make the process feel less overwhelming and help you see the progress you're making along the way. Your goals can change as your circumstances do, too, so there's no need to have everything figured out from the start.
#19
#20
Take out what you want to spend that week, e.g. $200. A lot of frivolous spending goes away when you have to pull out the only cash you have and look and it and think what you need for the rest of the week.